A pipe fails overnight, the floor is wet by morning, and the first question is almost always the same. Will insurance pay for this? Nobody can answer that without reading your policy, but the general rules are well known, and knowing them before you call your insurer helps you avoid costly mistakes.
This guide covers how insurers usually sort water damage, what to document, what your policy may expect you to do right away, and where a restoration company fits. It's general information for Temple City homeowners, not legal or claims advice. Your policy wording and your insurer make the final call, so read yours or ask them directly.
How insurers usually sort water damage
Most claims turn on one word: cause. Standard homeowners policies often cover water damage that is sudden and accidental, such as a supply line that bursts, a water heater that fails, or a washing machine hose that splits. They often do not cover damage from a leak that ran for weeks or months, or from wear and neglect that a homeowner could have caught.
The line between the two is not always clear. A slow drip behind a wall might be called gradual, while the same pipe letting go all at once is sudden. Adjusters look at evidence such as staining, rust, rot and mold growth to decide which one they're looking at.
Policies also differ on details. Some cover the water damage but not the failed pipe itself. Some limit sewer or drain backup unless you added an endorsement. Deductibles apply to nearly everything. Ask your agent which of these your own policy contains.
Covered or not: a quick decision table
Use this table as a list of questions to ask, not as an answer. The middle column uses the kind of cautious wording that fits, because only your policy and your insurer can say for certain.
| Situation | Coverage outlook | What to check in your policy |
|---|---|---|
| Supply line or pipe bursts suddenly | Often covered | Whether the failed pipe is included, and your deductible |
| Water heater tank fails | Often covered | Maintenance or age conditions in the wording |
| Washer or dishwasher hose splits | Often covered | Whether the appliance itself is covered |
| Slow leak under a sink for months | Often not covered | Gradual leak or continuous seepage exclusions |
| Roof leak during rain | Check your policy | Roof condition and wear or maintenance language |
| Sewer or drain backup | Check your policy | Whether a water backup endorsement was added |
| Rising floodwater or surface water | Often not covered | Whether you hold a separate flood policy |
| Damage from long-ignored maintenance | Often not covered | Neglect and wear exclusions |
If your situation lands in the middle, don't decide for yourself that it isn't covered. Ask the insurer for a determination in writing and let them cite the policy language.
Water in the house right now? Our dispatch line is open 24/7.
☎ Call (626) 879-0276Flood is a separate question
The California Department of Insurance says plainly that standard homeowners' insurance does not cover flood damage. Standard policies typically exclude flood, mudslide and debris flow. Flood coverage generally comes through the National Flood Insurance Program, a FEMA program sold by licensed agents and Write Your Own insurers.
There's a timing catch. A flood policy generally takes effect 30 days after purchase, with an exception when a lender requires it for a mortgage in a high-risk area. Coverage bought once a storm is already on the radar usually arrives too late for that storm. The Department does not regulate the NFIP, so program questions go to your agent or the program.
Cause still matters here. Water from a burst pipe inside the house is a plumbing loss, not a flood. Water that arrives from outside as surface water is the kind of event flood policies address. Ask your insurer how it classifies your event before you assume either way.
Document the damage before anything moves
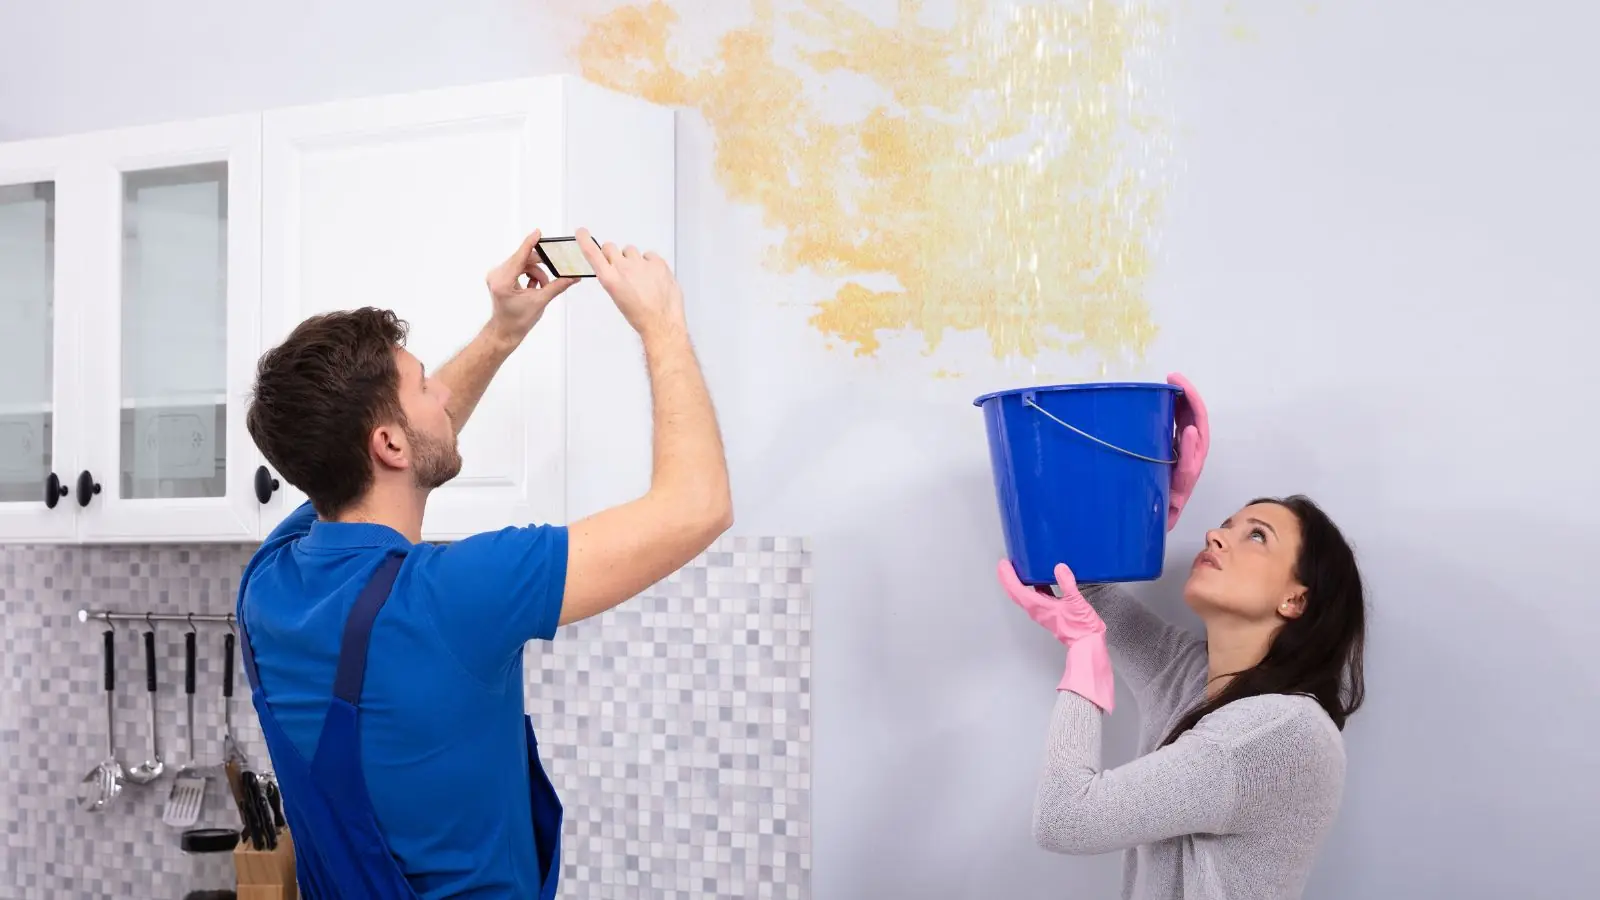
Good documentation is the most useful thing you can hand an adjuster. Start as soon as it's safe to enter the room. If water has reached outlets or the electrical panel, stay out and call your utility or 911 first.
- Take wide photos of each affected room, then close-ups of walls, floors, ceilings and contents.
- Record a slow walk-through video and narrate what you see.
- Photograph the source, such as the failed pipe, valve or hose, before anyone repairs it.
- List damaged items with rough age and purchase details, and keep receipts if you have them.
- If it's safe, keep damaged items until the adjuster has seen them. Remove only what is a hazard or will spoil, and photograph it first.
- Ask your restoration company for moisture readings and a written scope of work.
Moisture meters and thermal imaging cameras show where water traveled inside walls and under floors, which photos alone can't. A written scope with those readings gives the adjuster measurements instead of impressions. It supports your claim, though the insurer still decides.
Your duty to limit further damage
Many policies expect you to take reasonable steps to prevent more damage after a loss. In plain terms, that often means shutting off the water, removing standing water and starting the drying process rather than waiting for a claim appointment. Check your policy for the exact wording, since each one handles this differently.
There's also a practical reason to act. The EPA says drying wet materials within 24 to 48 hours of a leak usually prevents mold growth. A week of waiting can turn a drying job into a demolition job, and an insurer may question damage that grew while nothing was done. Our water mitigation service page explains what that first stage involves.
Keep receipts for emergency work and tell your insurer you're starting it. Ask whether they want to see anything first, and photograph before you discard.
Working with your adjuster and your contractor
Your restoration company works for you, not for the insurer. A reputable one explains scope and price before work starts, shows you the readings and gives you paperwork you can pass along. Be wary of anyone who promises approval or says the insurer will cover everything, because no contractor controls that decision.
LA County's consumer affairs department advises a written contract that states the total price, payment schedule, scope of work, timeline and the contractor's CSLB license number. You can verify any license at cslb.ca.gov. Cleanup and rebuilding may be estimated separately, since water damage cleanup removes wet materials while rebuilding drywall and flooring is repair. A scope that separates them is easier to compare against the adjuster's estimate.
Insurance Questions for Temple City Homeowners
Temple City sits at the base of the San Gabriel Mountains, which is why some owners wonder about flood coverage. Whether your address has flood exposure is a map question, not a guess. Look it up at the FEMA Flood Map Service Center at msc.fema.gov, and ask LA County Public Works or the city about drainage near you before deciding whether a flood policy makes sense.
Because a flood policy generally takes 30 days to take effect, that research belongs in a calm month, not during a storm. The same plumbing-versus-flood distinction applies if you own property in a neighboring city, if you're comparing water damage restoration in San Marino or water damage restoration in Arcadia. Flood maps are address-specific, so check each property separately.
Frequently asked questions
Sudden and accidental pipe failures are often covered, though your deductible and policy exclusions apply. Some policies pay for the water damage but not the repair of the pipe itself. Read the water damage section of your policy or ask your agent.
That depends on your specific address, not the city as a whole. Check the FEMA Flood Map Service Center at msc.fema.gov and ask LA County Public Works or the city about drainage near you. If you buy a policy, remember it generally takes effect 30 days after purchase.
Stop the source and remove standing water, because most policies expect you to limit further damage. Take photos and video first, and keep damaged items that are safe to keep until the adjuster has seen them. Ask your insurer if you're unsure what to hold back.
A company can provide moisture readings, photos and a written scope that you pass to your adjuster. The claim itself stays between you and your insurer, and no contractor can promise how it turns out. Be cautious of anyone who says otherwise.
Ask for the denial in writing with the specific policy language cited. You can ask the insurer to review it with your documentation, and the California Department of Insurance offers help to consumers with claim disputes. Keep drying records, since they show what the damage looked like.
Questions about your home? Talk to the 24/7 dispatch line.
☎ Call (626) 879-0276